
THE REEL REPORT
South Africa's Slot Machines Navigate a Complex Regulatory Landscape
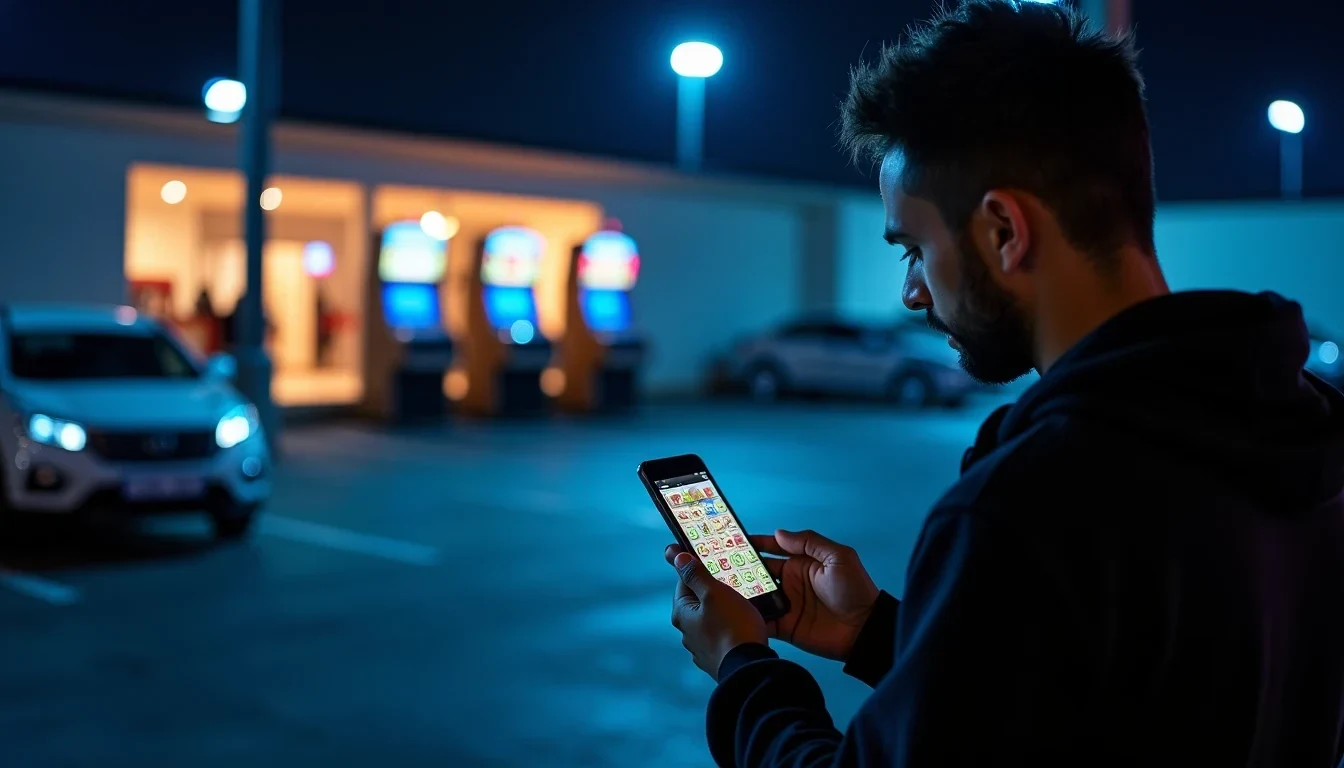
South Africa runs one of the stranger gambling regimes on the planet. Walk into GrandWest in Cape Town or Montecasino in Johannesburg and you will find thousands of slot machines humming under full provincial licence. Their operators pay taxes to nine different gambling boards, their jackpots are audited, and their payout percentages are verified. Open your phone from the same parking lot and try to spin a legal online slot, and you have crossed into territory where no licence exists, no regulator will hear your complaint, and the operator faces prison if caught. The country built a meticulous land-based machine and then, deliberately, built nothing for the digital equivalent. That contradiction is not accidental. It is the product of a regulatory system designed in 2004 for a world that no longer exists, and the strain is showing.
The National Framework and Its Provincial Fracture
The National Gambling Act of 2004 remains the spine of South African gambling law. It created the National Gambling Board, an oversight body that coordinates policy and monitors compliance. It does not itself issue casino licences or collect gambling taxes. That power sits with nine Provincial Gambling Boards, each operating under its own provincial act or ordinance. The rules change at provincial borders, altering how operators run their floors.
Gauteng, KwaZulu-Natal, and the Western Cape hold the country’s densest concentrations of licensed casinos. Their boards have developed distinct personalities through years of precedent. The Gauteng Gambling Board, operating under legislation dating to 1995, maintains aggressive deployment quotas for Limited Payout Machines in pubs and clubs. The Western Cape Gambling and Racing Board has historically taken a harder line on new casino licences, protecting the existing integrated resorts from saturation. KwaZulu-Natal’s board has wrestled with coastal tourism dynamics, balancing casino expansion against the seasonal fluctuation of visitor numbers. These are not cosmetic differences. They determine how many machines a venue can hold, what hours they operate, and what percentage of Gross Gaming Revenue disappears into provincial coffers before the operator sees a cent.
Tax rates on GGR vary by province and sometimes by revenue tier within a province, ranging from roughly 6% to north of 20% for certain machine categories. An operator running identical slot banks in Johannesburg and Durban can face meaningfully different effective tax burdens. That arithmetic shapes everything from floor layout to jackpot seeding to whether a property renovation pencils out. The National Gambling Board’s role is largely supervisory, stepping in when provincial decisions threaten national policy coherence or when cross-border regulatory disputes arise. For day-to-day commercial reality, the provincial board is the government that matters.
Who Actually Runs the Floors
Two groups dominate South African casino slot operations to a degree that would raise antitrust eyebrows in many jurisdictions. Sun International controls sixteen licensed casinos including GrandWest, Sibaya, and Carnival City. Tsogo Sun Gaming operates thirteen, among them Montecasino, Gold Reef City, and Silverstar. Together they account for the overwhelming majority of legal slot positions in the country.
Both operators long ago abandoned the pure gambling hall model. Their properties are integrated resorts by deliberate strategy, wrapping casinos inside hotels, conference centres, retail arcades, and entertainment venues. The slot floor is the revenue engine, but it is not the product being sold. The product is a complete evening out, and the slots are positioned as one component among many. This affects game design. A player who drove two hours to Montecasino for a show and dinner does not want to decode elaborate bonus mechanics. They want immediate visual feedback, clear jackpot displays, and the ability to play at low denominations without feeling marginalised.
Sun International’s Sun MVG programme and Tsogo Sun’s Rewards programme represent the operational backbone of this approach. Both are tiered loyalty systems tracking play across properties, offering personalised incentives, room upgrades, and exclusive event access to high-value players. The data harvested through these programmes feeds directly into floor decisions: which machines get premium placement, which new titles merit trial, and which underperformers get cycled out. The operators know their player base with precision that offshore online sites, operating illegally and without verified identity systems, cannot match.
Below the casino tier sits a separate ecosystem of Limited Payout Machine operators. Vukani Gaming, a Sun International subsidiary, and Goldrush Group deploy thousands of LPMs in licensed pubs, clubs, and smaller venues across multiple provinces. These machines carry lower maximum bets and capped payouts than their casino counterparts. They reach demographics and geographies that integrated resorts cannot. The LPM market operates under its own provincial deployment rules, with strict limits on machines per venue and requirements for separation from areas where minors might gather. For many South African players, the LPM in a neighbourhood social club is the only legal slot they will ever touch.
What South African Players Actually Want
The country’s slot market reflects its demographic complexity in ways that defy easy generalisation. Eleven official languages, vast income inequality, and sharply different urban and rural experiences mean that no single game design dominates. Yet certain patterns emerge consistently across operator data and property observations.
Simplicity sells. South African players, across income levels, show strong preference for straightforward mechanics with visible paytables and immediate comprehension. Elaborate cascading reel systems or multi-layered bonus games that require tutorial screens tend to underperform relative to classic three-reel formats or simple five-reel video slots with single bonus events. This is partly a function of the social environment; many players are in groups, conversing, moving between gaming and other resort activities. A game that demands sustained attention to its internal logic interrupts the experience rather than enhancing it.
Local theming carries genuine weight. Games featuring African wildlife, particularly the “Big Five” species, or drawing on recognisable cultural narratives and historical figures, outperform generic international titles in head-to-head floor tests. This is not mere patriotic preference. These themes create immediate visual recognition in a market where English is not universally a first language, reducing the cognitive load of engagement. A lion symbol needs no explanation. A mythological figure from unfamiliar European folklore does.
Progressive jackpots remain the single most powerful draw across all player segments. The aspirational mathematics of a life-changing payout, however statistically remote, transcends the country’s economic stratification in ways that surprise some international observers. Operators seed progressives aggressively because they drive floor traffic and session length more reliably than any other promotional tool. The progressive meter, ticking upward on a prominent display, is the closest thing in physical slot design to the viral mechanics that dominate online engagement.
Multi-denomination machines are essential infrastructure. A single bank must accommodate players betting fractional Rand amounts alongside others wagering at significantly higher levels, often simultaneously. The social taboo around visible betting disparities that exists in some markets is less pronounced in South Africa, but the practical need for flexible denomination selection remains acute. Operators configure their floors carefully around this requirement, often clustering machines by typical denomination range to manage player flow and machine utilisation.
The Economic Footprint
South Africa’s regulated slot industry supports more than 40,000 direct jobs, from floor technicians and customer service staff to security personnel and senior management. The indirect employment multiplier is substantial, spanning construction, hospitality supply chains, maintenance services, and local procurement. In provinces where unemployment rates regularly exceed 30%, casino complexes rank among the more reliable formal employers in their regions.
The fiscal contribution is equally significant. The gambling industry’s Gross Gaming Revenue runs to billions of Rand annually, with slot operations generating the largest single share. Provincial governments depend on gambling taxes as a revenue stream that, unlike income tax, is collected at source and difficult to evade. The effective tax rates, while variable, are high enough that provincial treasuries notice their absence. Several provinces have faced budgetary pressure during casino licence renewal negotiations, aware that a relocated or closed property would leave a hole in planned expenditure.
Corporate Social Responsibility spending, while partly voluntary and partly licence-mandated, channels millions of Rand annually into education, healthcare, and small enterprise development in casino-adjacent communities. Sun International and Tsogo Sun both maintain dedicated foundations and community liaison structures. The sincerity of this spending is debated by critics who note its public relations value, but the material flows are real. Roads get built. Bursaries get awarded. Local suppliers get contracts. Whether this compensates for the social costs of gambling expansion is a separate argument, but the economic presence is not hypothetical.
Infrastructure investment represents another undercounted contribution. Casino developments typically require substantial private expenditure on access roads, utilities, and public space improvement that benefits surrounding areas regardless of whether those residents ever enter the gaming floor. GrandWest’s construction in the late 1990s transformed a nondescript Cape Town suburb into a significant entertainment destination. Montecasino’s development in Fourways effectively created the commercial centre of that corridor.
The Online Absurdity
South Africa’s regulatory architecture becomes genuinely strange here. The same National Gambling Act of 2004 that meticulously structures land-based slot operations explicitly prohibits “interactive gambling,” a term that covers online casinos, online poker, and specifically online slots for real money. No licensing framework exists. No regulator could issue one if it wanted to. The prohibition targets operators rather than individual players, but the practical effect is a total legal vacuum for digital slot play.
South African players access offshore online slot sites in substantial numbers. These operators, typically licensed in Malta, Curaçao, or other jurisdictions, accept Rand deposits and market aggressively through affiliate networks and social media. Their legal exposure under South African law is real; the NGA provides for substantial fines and imprisonment for entities offering interactive gambling to residents. Enforcement, however, is complicated by jurisdictional limitations and the technical ease of site blocking circumvention. The result is a tolerated illegality, widespread, unregulated, and structurally precarious for participants.
The risks to players are not abstract. Unlicensed operators can and do manipulate return-to-player percentages without independent verification. Withdrawal delays or outright refusals are common complaints in player forums. Identity theft and payment fraud occur at rates that would trigger regulatory intervention in any licensed jurisdiction. Most critically, the responsible gambling infrastructure that land-based operators are required to maintain—self-exclusion programmes, play limits, staff intervention training—simply does not exist on offshore sites. A player showing signs of problematic behaviour in a Sun International property will encounter trained staff and formal support pathways. The same player at an unlicensed online operator will encounter automated marketing emails encouraging continued play.
The policy incoherence is striking. South Africa has built one of the more competent land-based regulatory systems in the developing world, with genuine consumer protection, verified game fairness, and substantial tax collection. It has simultaneously created conditions where digital players are driven into an unregulated wild west, generating no tax revenue and offering no recourse when things go wrong. The 2004 Act’s drafters could not have anticipated the smartphone revolution, but the failure to amend the framework in two decades of accelerating digital adoption represents a specific political choice, or more precisely, a specific political paralysis.
The Operational Reality for 2024 and Beyond
South African slot operators face a landscape of constrained growth. Provincial licence caps are largely fixed. New casino development requires navigating boards that have become more cautious about market saturation. The LPM sector offers some expansion headroom but faces its own political sensitivities around gambling accessibility in working-class communities. Sun International and Tsogo Sun have both pursued property refurbishment and technology upgrade cycles to extract more value from existing positions rather than expanding their footprints.
The online prohibition creates particular strategic tension. Both major operators have international digital gambling interests through separate corporate structures, Tsogo Sun through historical connections to UK betting operations, Sun International through African regional expansion. They possess the technical capability and player databases to launch credible online slot offerings. They are legally barred from doing so in their home market. This creates a competitive absurdity where illegal offshore operators, paying no South African tax and subject to no South African regulation, capture digital player value that licensed domestic operators cannot touch.
Provincial regulatory divergence continues to complicate national strategy. A machine configuration approved in Gauteng may require modification for Western Cape compliance. Tax rate changes in one province can shift capital allocation decisions that affect development timelines elsewhere. The National Gambling Board’s coordination role has not eliminated these frictions, and the constitutional division of powers means it cannot. Operators have learned to manage this complexity as a cost of doing business, but it remains a genuine competitive disadvantage relative to more unified regulatory environments.
The cultural and demographic factors that shape game preference show no signs of shifting. South African players continue to reward simplicity, local recognition, and jackpot aspiration. International game suppliers entering the market have learned, sometimes painfully, that successful titles elsewhere require substantial adaptation for South African floors. The integrated resort model, with slots embedded in broader entertainment propositions, remains robust against both economic pressure and potential future digital competition.
What happens next depends largely on whether the political system can address the online prohibition. The current arrangement serves nobody well except the offshore operators profiting from regulatory failure. Licensed land-based operators are denied a growth channel. Players are denied consumer protection. The treasury is denied revenue. The status quo persists because amending the NGA requires legislative bandwidth that competing priorities have consistently absorbed, and because the moral politics of gambling expansion remain treacherous for elected officials. The longer the contradiction persists, the more the land-based regulatory achievement is undermined by its digital absence. South Africa built a machine that works. It just built it for a world that is disappearing.